
Why mapping income to expenses matters on a fixed income
Retirement income is usually predictable in a way that working income is not: Social Security arrives on the same Wednesday every month, a pension check clears on the first of the month, and an RMD schedule can be calculated a year in advance. That predictability is genuinely useful. A written budget turns that regularity into a plan rather than a hope.
Without a budget, many retirees spend comfortably early in the month and feel stretched by the third week, not because income is too low, but because irregular expenses arrived without a reserved place in the plan. Mapping income to expenses before the month begins changes that pattern.
This article walks through the process in six steps. It is general financial education and is not personalized financial advice. For decisions specific to your situation, a licensed financial adviser or a nonprofit credit counseling agency can provide guidance tailored to your circumstances.
What you need before you start
Gathering the right documents before you sit down to build a budget saves time and produces more accurate numbers. You will want recent statements for every income source and at least three months of bank or credit card records showing actual spending.
What you will need
For general guidance on personal finance topics, the Finance section of this site covers a range of topics relevant to retirement planning.
Tools that make the process easier
Printed or digital spreadsheet
Organizes income and expense categories side by side so gaps are visible at a glance.
Bank and account statements (3 months)
Reveals actual spending patterns rather than estimated ones.
Social Security my Social Security account
Lets you verify your current monthly benefit amount directly from the Social Security Administration.
Calendar or planner
Tracks the dates different income sources arrive so bills can be scheduled accordingly.
Step-by-step: building your retirement budget
List every income source and its monthly amount
Write down each source of income you currently receive or expect to receive, along with the net amount (after taxes or Medicare premium deductions) that actually reaches your bank account. Common sources include:
- Social Security retirement benefits
- Pension or annuity payments
- Required minimum distributions (RMDs) from IRAs or 401(k) accounts
- Part-time or freelance earnings
- Rental income
- Veterans benefits or railroad retirement
If any amount varies month to month, use a three-month average rather than guessing a high or low figure. Add the amounts together to get your total monthly income.
Categorize and total your fixed monthly expenses
Fixed expenses are costs that stay the same (or nearly the same) each month. List each one and its amount:
- Rent or mortgage payment
- Property taxes, if paid monthly or escrowed
- Homeowners or renters insurance
- Medicare Part B and Part D premiums
- Supplemental or Medicare Advantage plan premiums
- Car payment or lease
- Auto and home insurance
- Subscriptions (phone plan, internet, streaming services)
Total these to see how much of your monthly income is committed before you spend a single dollar on food or utilities.
Estimate variable monthly expenses from actual statements
Variable expenses change from month to month. Pull three months of bank and credit card statements and calculate a realistic average for each category:
- Groceries and household supplies
- Utilities (electricity, gas, water)
- Gasoline or public transit costs
- Out-of-pocket medical and dental costs
- Clothing
- Dining out and entertainment
- Gifts and donations
Do not estimate from memory alone. Actual statements often reveal spending that surprises people, and an honest number is more useful than a comfortable one.
Add an irregular expense reserve to your monthly plan
Some costs do not arrive every month but are entirely predictable over the year: car registration, annual insurance premiums paid in a lump sum, home maintenance, holiday gifts, and dental work. List these annual or semi-annual costs, add them together, and divide by 12. Set that monthly amount aside as a separate line in your budget labeled something like "irregular expenses reserve."
Without this step, a $600 car repair or a $400 dental copay can disrupt two or three months of otherwise balanced spending.
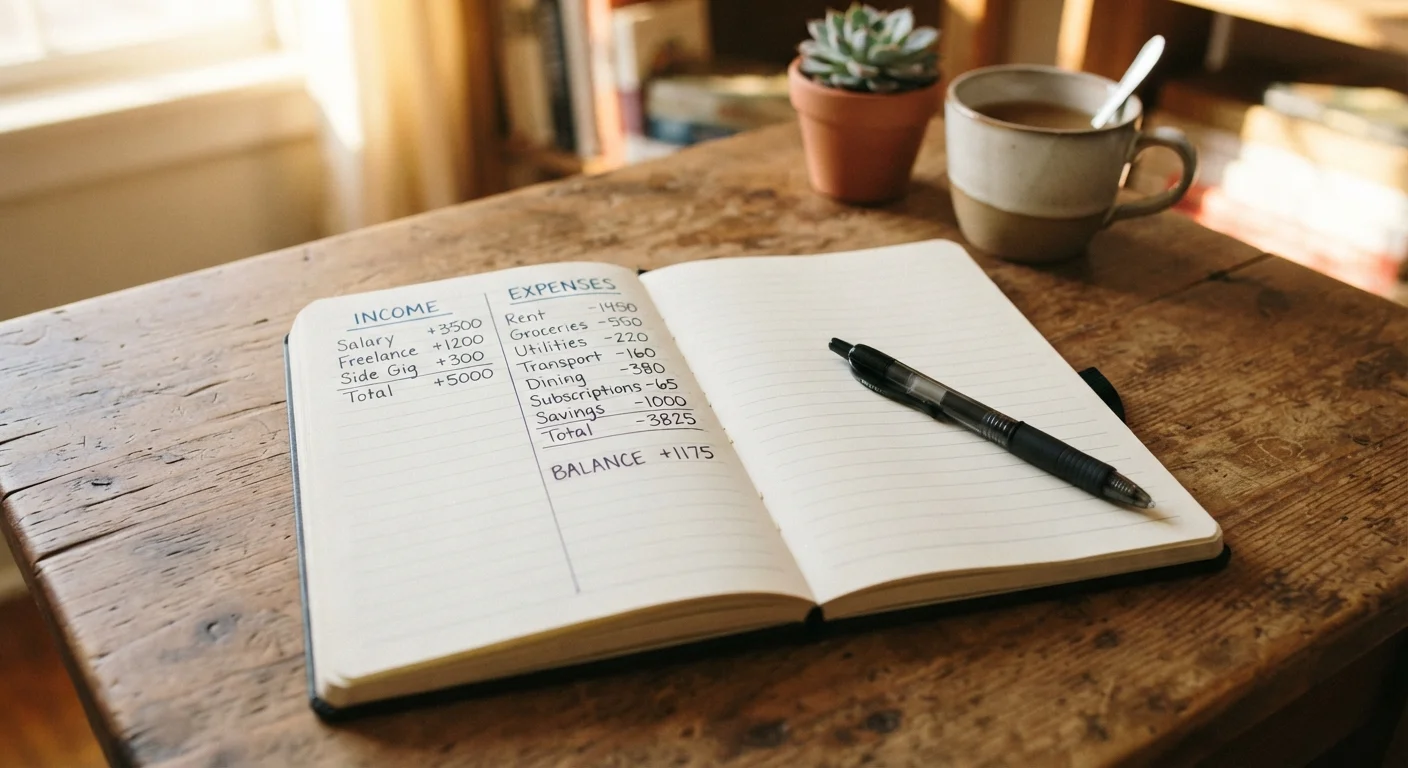
Compare total income to total expenses and identify the gap
Subtract your total monthly expenses (fixed, variable, and the irregular reserve) from your total monthly income. The result tells you one of three things:
- A positive number means you have discretionary room each month.
- Zero means your budget is balanced but has no buffer for surprises.
- A negative number means expenses currently exceed income, and a spending or income adjustment is needed.
A negative result is not a reason for alarm, but it does call for a clear-eyed look at which expenses can be reduced and whether any income sources have not yet been activated, such as a pension benefit or a spousal Social Security benefit you have not yet claimed. For guidance on how claiming age affects your monthly Social Security amount, see our overview of Social Security benefits.
Review and adjust the budget every six months
Costs change. Medicare premiums adjust each January. Utility rates shift with the seasons. A new prescription can alter out-of-pocket medical spending. Set a reminder to revisit your budget at least twice a year and after any significant life change, such as a move, a new health condition, or the loss of a household member's income.
Housing costs are often the largest single line in a retirement budget. If your current housing arrangement no longer fits your finances or daily needs, a review of alternatives is worth the effort. See our comparison of aging in place and assisted living for a look at the financial trade-offs involved in that decision.
This article is for general informational and educational purposes only. It is not personalized financial, tax, legal, or investment advice. Consult a qualified, licensed professional for guidance specific to your circumstances.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.