
Why discounts often go unclaimed
Auto insurance premiums are not fixed. Insurers build discount programs into their rating systems, but many of those reductions only apply when you request them or when your insurer is made aware of qualifying information. A driver who never mentions a new safety course, a second policy, or a change in annual mileage may simply keep paying the original rate.
The programs below are common across many U.S. carriers, though availability, names, and savings amounts vary by insurer and by state. None of this is personalized insurance advice. For guidance on your specific policy, talk to a licensed agent. If you want to understand how underlying rating factors work before exploring discounts, see how each rating factor typically affects your premium.
Multi-policy bundling
Carrying more than one policy with the same insurer, such as auto and homeowners or renters coverage, frequently qualifies for a bundling discount. The insurer reduces administrative costs when managing multiple accounts for one customer, and part of that savings is passed along in the rate. The discount percentage varies widely, so it is worth comparing the bundled price against separate policies from different carriers to confirm you are actually paying less overall.
Bundling saves money only when the combined rate beats what separate carriers would charge.
Clean driving record
Most insurers reward drivers who have gone a set number of years without an at-fault accident or moving violation. The window is commonly three to five years. If a past incident has aged off your record, your insurer may not automatically recalculate your rate. Asking for a re-evaluation at renewal is a reasonable step. A lapse in coverage can work against this program, since gaps on your record affect how insurers view your risk. Understanding what a coverage lapse does to your rate is worth reviewing if that applies to you.
Insurers may not automatically lower your rate when a past incident ages off your record.
Defensive driving and safety courses
Completing an approved defensive driving course can qualify you for a premium reduction, and some states require insurers to offer this discount by law. Courses are available in person and online, and approval requirements differ by state and carrier. Older drivers should check whether their insurer recognizes mature driver courses, which are designed specifically for drivers over a certain age. Seniors face distinct rating considerations that make these programs worth looking into.
Some states legally require insurers to offer a discount for approved safety course completion.
Low annual mileage
Drivers who put fewer miles on their vehicles each year represent lower exposure for an insurer. Many carriers offer a low-mileage discount once annual mileage falls below a threshold, often somewhere around 7,500 to 10,000 miles. If your driving habits changed after retirement, a job change, or a move, and you never updated your insurer, your rate may not reflect your actual use. Providing an odometer reading at renewal is typically how this gets verified.
If your annual mileage dropped significantly, your insurer may not know unless you tell them.
Telematics and usage-based programs
Usage-based insurance programs track driving behavior through a mobile app or a plug-in device. Factors such as braking patterns, acceleration, time of day, and mileage feed into a score that can lower your premium. These programs tend to benefit low-mileage drivers and those who drive mostly during off-peak hours. The trade-off is that your insurer collects detailed driving data, which some policyholders are uncomfortable with. Comparing usage-based and traditional insurance models in more detail can help you decide if it fits your situation.
Telematics programs collect real driving data, so the privacy trade-off is worth considering before enrolling.
Vehicle safety features
Cars equipped with anti-lock brakes, airbags, anti-theft systems, and newer driver-assistance technologies may qualify for feature-specific discounts. The insurer's logic is straightforward: safety equipment reduces the likelihood of injury claims, and anti-theft systems reduce theft-related losses. These discounts are usually applied automatically when you add a newer vehicle to a policy, but confirming that the insurer has your vehicle's full features on file is a reasonable check.
Anti-theft and safety feature discounts are often automatic, but verifying what is on file is a good habit.
Good student discount
Young drivers are statistically among the most expensive to insure. Many insurers reduce premiums for full-time students who maintain a grade point average at or above a set threshold, commonly a B average or 3.0 GPA. The discount typically applies through age 24 or until the student is no longer enrolled. Proof of grades, such as a transcript or report card, is usually required at each renewal. If a young driver is on a parent's policy, the parent is the one who needs to request and submit documentation.
Young drivers who maintain a B average or better may qualify for a meaningful premium reduction.
Paying in full and paperless billing
Paying your annual or semi-annual premium in a single lump sum instead of monthly installments removes the administrative cost of processing multiple payments. Many insurers pass some of that savings back as a paid-in-full discount. Separately, switching to electronic statements and automatic payments can each earn a small additional reduction. These are modest individually, but combined with other programs, they add to the overall effect.
Paying your full premium upfront removes installment fees and often earns a direct rate reduction.
Getting the most from what you qualify for
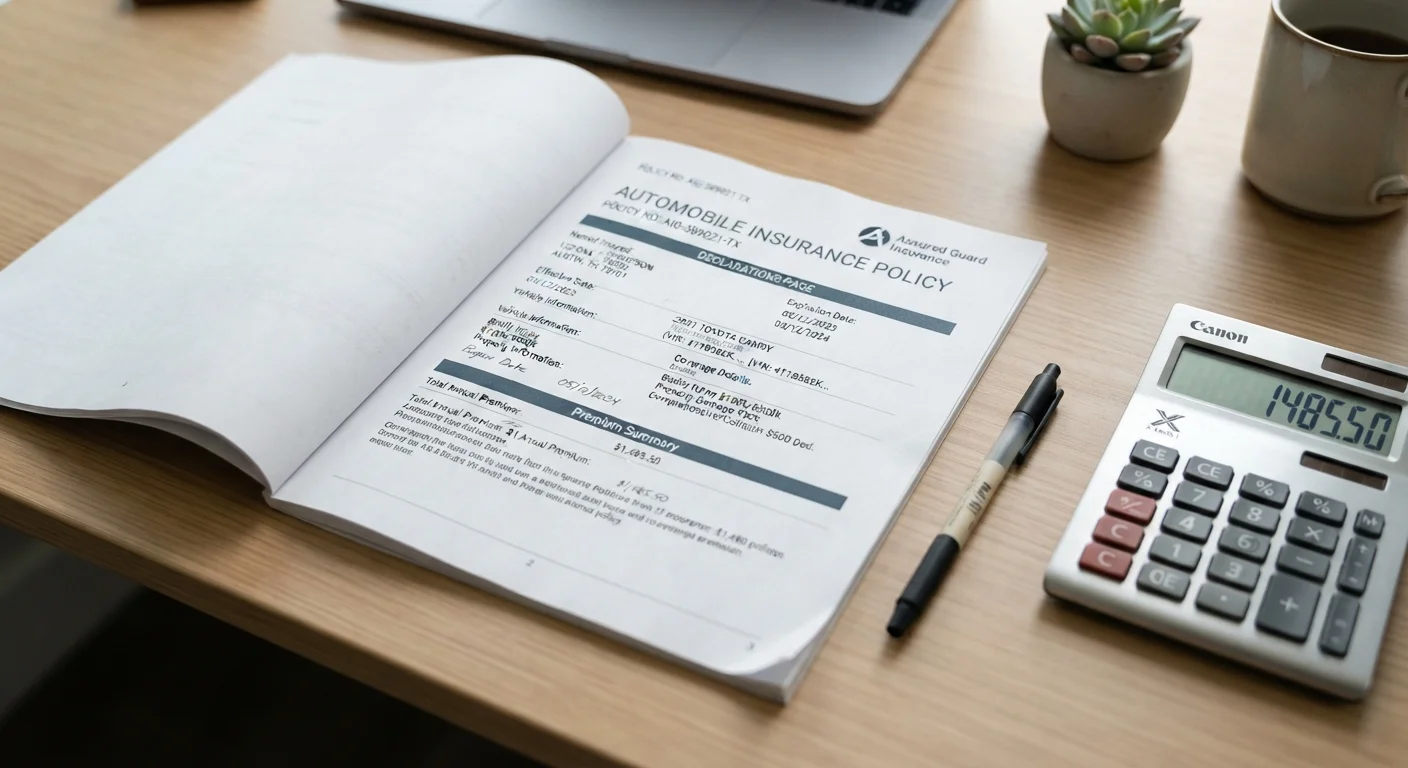
A single discount rarely moves the needle much on its own. Where drivers see meaningful reductions is when several smaller discounts apply at once. Before your next renewal, pull your declarations page and check which programs are already applied and which ones you might now qualify for. Reading your declarations page carefully makes that review faster.
If your premium has climbed and discounts alone do not close the gap, a higher deductible is another lever worth understanding. Weighing the trade-offs of a higher deductible before making that change can help you avoid taking on more out-of-pocket risk than makes sense for your situation.
This article is for general informational purposes only and is not personalized insurance or financial advice. Coverage terms, discount availability, and eligibility requirements vary by insurer and state. Consult a licensed insurance agent or adviser for guidance specific to your circumstances.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.