
Why policy documents feel so dense
Auto insurance policies are legal contracts, and legal contracts are written with precision in mind, not readability. A single policy can run 30 to 60 pages, combining standardized forms (called ISO forms in the industry) with state-specific amendments and insurer-specific endorsements. That layered structure is what makes them confusing, but it also means every policy follows a broadly predictable order once you know what to look for.
Reading your policy before you need to file a claim is the most practical thing you can do. Surprises at claim time, such as discovering a coverage gap or an exclusion you missed, are far harder to address than surprises caught during a quiet review at home.
This article is for general informational purposes only. It is not personalized insurance, financial, or legal advice. Coverage terms, exclusions, and requirements vary by insurer and by state. Read your actual policy documents and consult a licensed insurance agent or adviser for guidance specific to your situation.
How to work through your policy step by step
Your policy is a legal contract
Every word in an auto insurance policy has legal weight. If you have questions about specific language, coverage gaps, or exclusions, contact your insurer's customer service line or a licensed insurance agent before you assume coverage exists. General articles like this one provide education, not personalized insurance advice.
What you will need
Start with the declarations page
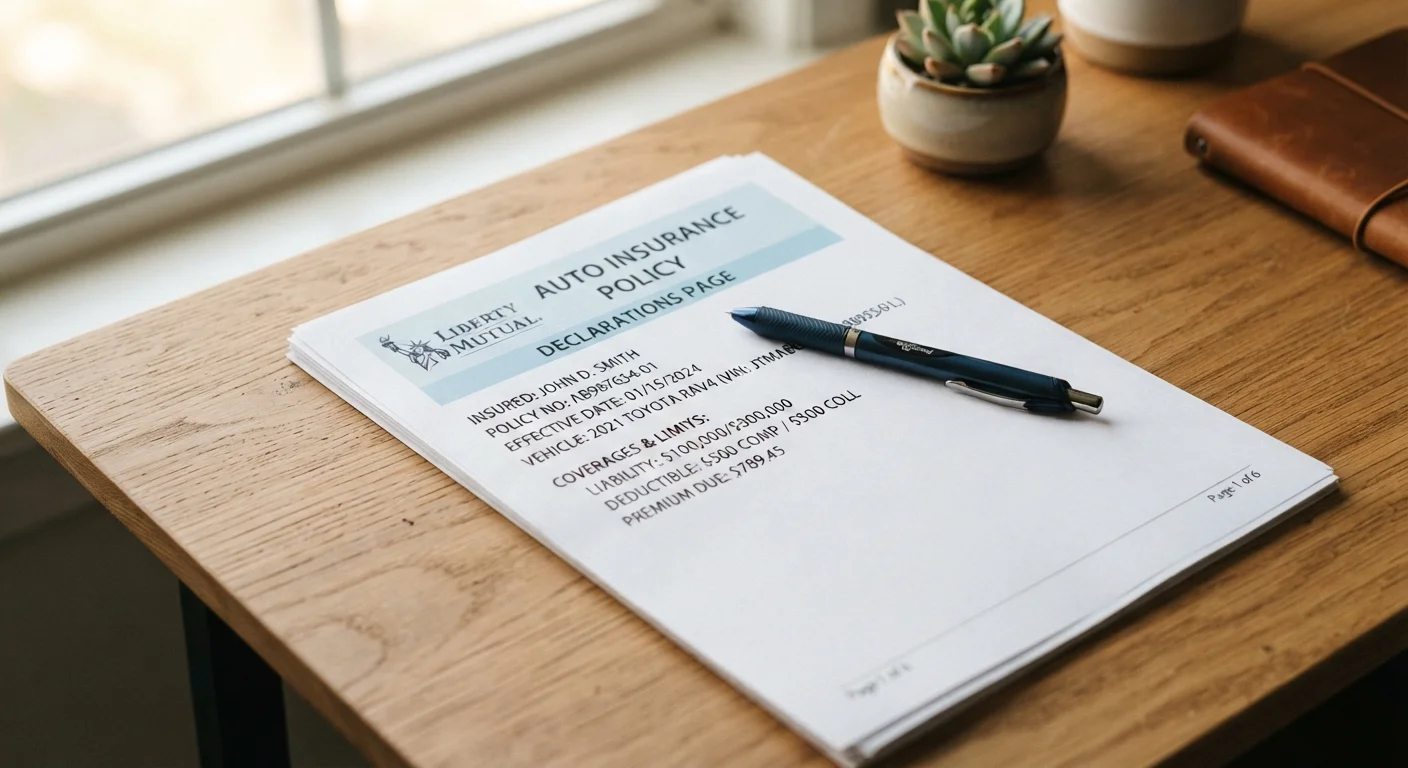
The declarations page (often called the "dec page") comes first in most policies. It gives you a snapshot of the entire contract: your name, the insured vehicles, policy period, coverage types, coverage limits, and the total premium. If a number elsewhere in the policy conflicts with the dec page, flag it and call your insurer to clarify.
Confirm that every vehicle you own is listed and that the listed address matches where the car is primarily kept. Insurers use garaging location as a rating factor, so a mismatch can affect both your rate and a future claim.
Understand the coverage sections
After the dec page, the policy body describes each coverage type in detail. Common sections include:
- Liability: Pays for injuries or property damage you cause to others. Limits appear as three numbers (for example, 25/50/25), representing per-person bodily injury, per-accident bodily injury, and property damage maximums in thousands of dollars.
- Collision: Covers damage to your vehicle from a crash, regardless of fault. Your deductible applies before the insurer pays.
- Comprehensive: Covers non-collision damage such as theft, hail, or a fallen tree. A separate deductible usually applies.
- Uninsured/underinsured motorist: Steps in when the at-fault driver has no coverage or not enough to cover your losses.
- Medical payments or personal injury protection (PIP): Pays medical costs for you and passengers, regardless of fault. PIP is required in some states.
Each section will state its limit and deductible. Write these down so you can compare them to your state's minimums and to your own financial exposure.
Read the exclusions carefully
Exclusions define what the policy will not cover. They are typically listed in a dedicated section, sometimes titled "What is not covered" or buried within each coverage section. Common exclusions include: intentional damage, using your personal vehicle for ride-share or delivery work, and damage from wear and tear.
If you drive for a ride-share platform, your personal policy likely excludes coverage while you are logged in to the app. A separate commercial endorsement or a ride-share gap policy addresses this. Always read exclusions before assuming a loss will be covered.
Check for endorsements
Endorsements (sometimes called riders or amendments) modify the base policy. They can add coverage, remove it, or change a term. Common endorsements include rental reimbursement, roadside assistance, gap coverage for a financed vehicle, and new car replacement.
Each endorsement has its own premium listed on the dec page. If you see charges you do not recognize, match them to an endorsement page to confirm what you are paying for.
Locate the conditions and duties sections
The conditions section describes your obligations as a policyholder. It covers how to report a claim, cooperate with an investigation, and what happens if you miss a payment. Violating a condition can give the insurer grounds to deny a claim.
Pay attention to the reporting timeframe. Most policies require prompt notice after an accident. Waiting too long can complicate or invalidate a claim. Steps to take right after an accident can help you act quickly when it counts.
Note the definitions section
Most auto policies include a definitions section that explains how specific words are used throughout the document. Terms like "insured," "occurrence," and "covered vehicle" have precise meanings that determine whether a claim qualifies. When a coverage section references a defined term, flip back to definitions to read the exact language rather than relying on everyday meaning.
Review your policy at every renewal
Insurers can change terms, limits, or exclusions at renewal. A quick review each year catches changes before they affect you. If your situation has changed, such as adding a driver or buying a new vehicle, update your policy rather than assuming the existing terms still apply.
After you finish reading
Once you have read through the full document, make a short list of anything that is unclear and bring those questions to your insurer or a licensed agent. Common questions include whether a specific type of loss is covered, how a deductible applies when two coverages overlap, and what happens if someone not listed on the policy drives your car.
If you discover your coverage is thinner than you expected, renewal is a natural time to adjust limits or add endorsements. Discount programs can sometimes offset the cost of increasing your limits. For drivers who want a closer look at how age affects their coverage options, senior driver coverage considerations covers the factors most relevant to older policyholders.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.