
How age factors into auto insurance rates
Auto insurers use a range of variables to set premiums, and age is one of them. Statistically, drivers in their late teens and early twenties have higher crash rates, so they pay more. Rates generally drop through middle age, then can begin to rise again for drivers in their mid-70s and beyond, as some research links older age to increased crash risk per mile driven.
That said, age is never the only number in the equation. Your driving record, annual mileage, vehicle type, and location all factor in. See how each rating variable typically works for a fuller picture of what shapes your premium.
Some states restrict how much weight insurers can place on age alone. Regulations vary, so it is worth checking your state's insurance department website to understand what rules apply where you live.
Discounts seniors commonly qualify for
Several discount programs are open to older drivers, though eligibility rules differ by insurer and state.
- Defensive driving course discount: Many insurers reduce premiums for drivers who complete an approved refresher course. AARP and AAA both run widely recognized programs. The discount is usually modest, around 5 to 10 percent, but it renews if you repeat the course on the required schedule.
- Low mileage discount: Retired drivers often put fewer miles on their vehicles. Some insurers offer reduced rates for annual mileage below a set threshold, typically between 7,500 and 10,000 miles.
- Usage-based insurance: Telematics programs monitor driving habits such as braking, speed, and time of day. Drivers who log short, calm trips may see meaningful savings. Compare usage-based and traditional policies before enrolling, since the data collected can also raise rates if driving patterns score poorly.
For a broader look at available programs, review common premium-reduction options and ask your insurer which ones apply to your policy.
| Typical defensive driving discount | 5 to 10 percent off premium |
| Common low-mileage threshold | Under 7,500 to 10,000 miles per year |
| Who sets rate rules | State insurance departments regulate what factors insurers may use |
| Policy review frequency | At each renewal, or after a major life change |
Coverage decisions worth reviewing at this stage
Coverage needs can shift as driving habits change. A few areas are worth examining at each renewal period.
Collision and comprehensive on older vehicles
If your car has depreciated significantly, the payout from a collision or comprehensive claim may be less than the combined cost of the deductible and the ongoing premium. Some drivers drop one or both coverages on older vehicles for this reason. Understand the trade-offs of adjusting your deductible before making that call.
Medical payments coverage
This optional coverage (called MedPay in most states) pays medical costs after an accident regardless of fault. For seniors on fixed incomes, MedPay can fill gaps that health insurance leaves, such as copays and deductibles. The interaction between auto medical coverage and Medicare or a supplemental plan is worth discussing with a licensed insurance agent.
Policy accuracy
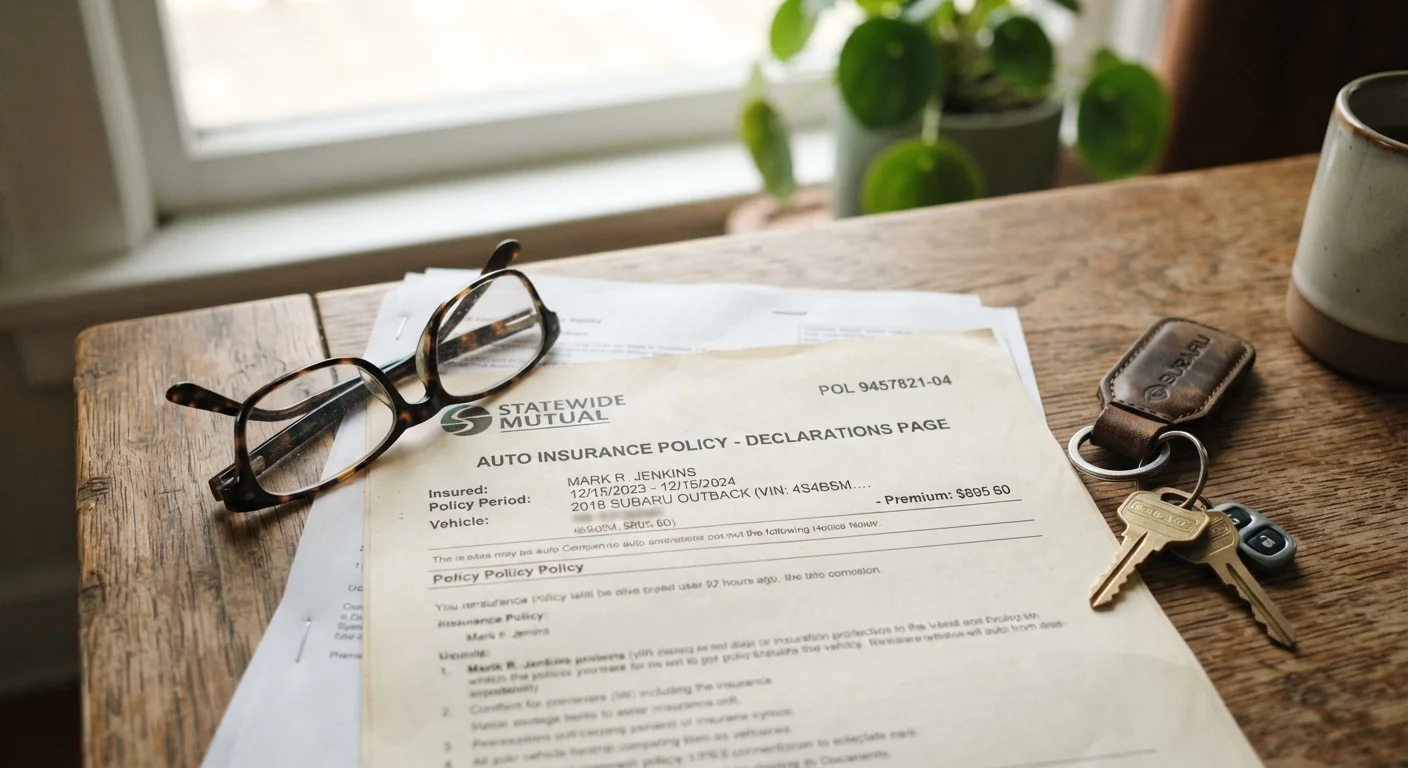
Outdated details on a policy can affect a claim. If your annual mileage has dropped after retirement, or if the primary driver listed no longer reflects reality, updating your policy keeps it accurate. Learn how to read each section of your policy so you know what to look for.
This article is for general informational purposes only and is not personalized insurance, financial, or legal advice. Coverage terms, eligibility, and regulations vary by insurer and state. Consult a licensed insurance agent or adviser for guidance specific to your situation.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.