
Summary
14 items · 30 to 60 minutes
How Medigap fits into Medicare
Original Medicare (Parts A and B) covers a wide range of hospital and medical services, but it leaves gaps: deductibles, coinsurance, and copayments that you pay out of pocket. A Medicare Supplement policy, commonly called Medigap, is private insurance that can cover some or all of those leftover costs.
Medigap works alongside Original Medicare, not instead of it. You must be enrolled in Medicare Part A and Part B before a Medigap policy can take effect. The policies do not include prescription drug coverage; for that, you would need a separate Part D plan. For a broader look at what Original Medicare does and does not pay for, see our article on common Medicare coverage misconceptions.
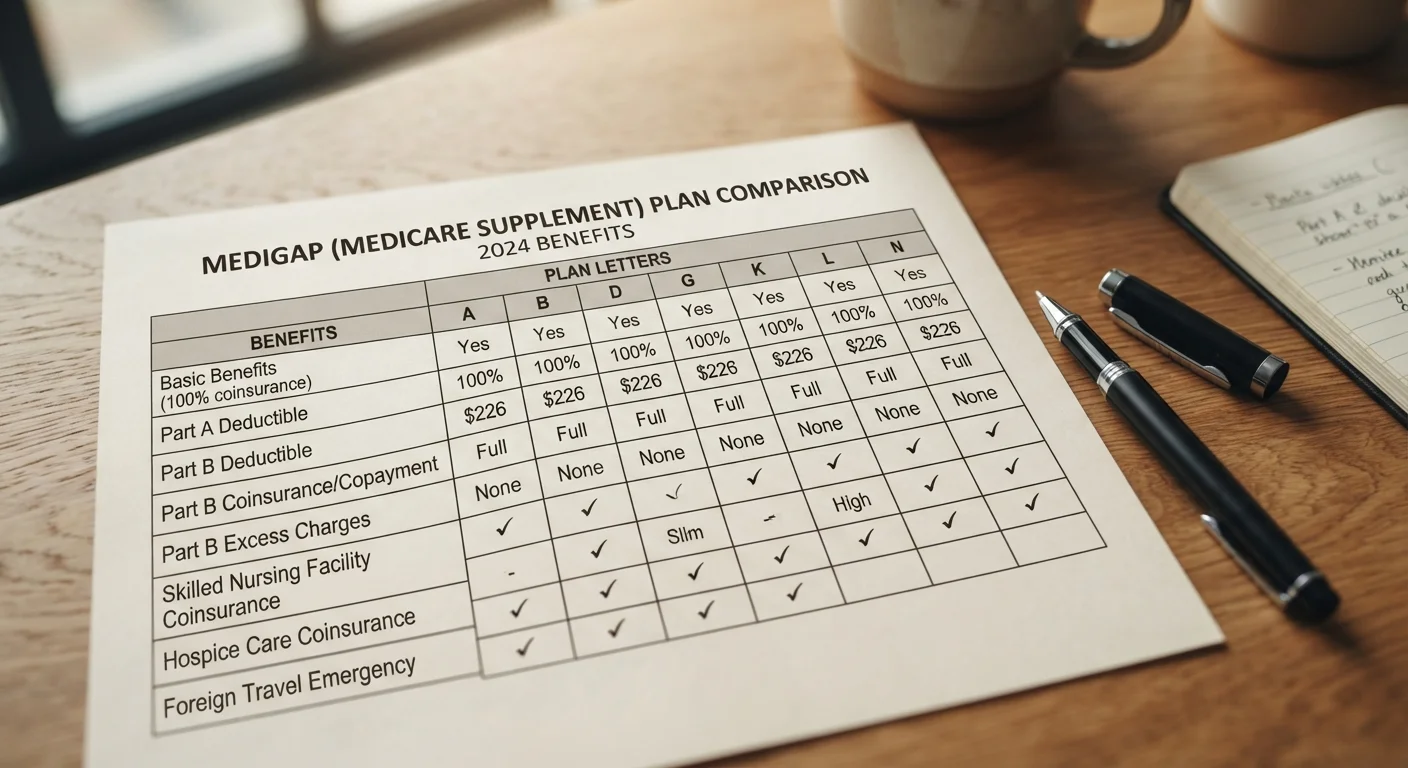
Understanding the structure of these plans before you start comparing them saves time and helps you ask better questions.
What to check before you compare plans
Before reviewing specific policies, gather a few pieces of information that will shape your choices: your Medicare enrollment dates, any chronic conditions or regular prescriptions, the names of your current doctors and whether they accept Medicare assignment, and a general sense of how often you use medical services in a year.
Knowing how Medicare and Medicaid interact can also matter for some households. Our comparison of Medicare and Medicaid covers who qualifies for each and how the two programs differ.
Understanding plan structure
Comparing costs
Checking insurer details
Before you finalize
Enrollment timing and your rights
The Medigap Open Enrollment Period is a six-month window that begins the month you turn 65 and are enrolled in Medicare Part B. During this window, insurers cannot use medical underwriting to charge you more or deny you a policy based on your health history. Outside this window, those protections generally do not apply in most states, though exceptions exist.
Some states offer additional guaranteed-issue rights or their own enrollment protections. Checking your state insurance commissioner's website gives you the most accurate picture of local rules.
Missing your enrollment window has lasting consequences
Outside your six-month Medigap Open Enrollment Period, insurers in most states can apply medical underwriting. That means they may charge higher premiums or decline to sell you a policy based on your health. Once this window closes, it generally does not reopen unless you qualify for a specific guaranteed-issue right. Plan ahead and do not assume you can wait.
If you are comparing your options during a general enrollment period rather than your personal Medigap window, the process in our guide to choosing a health plan during open enrollment covers related timing concepts that may help.
This article provides general information about Medicare Supplement insurance. It is not personalized insurance, financial, or legal advice. Coverage terms, premiums, and eligibility vary by state and insurer. Consult a licensed insurance agent or your State Health Insurance Assistance Program (SHIP) counselor for guidance specific to your situation.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.