
Why open enrollment decisions are worth your time
Health coverage affects your access to care and your finances for an entire year. A plan that suited you well before may no longer match your situation if your health, income, or household changed. Open enrollment is the one predictable opportunity each year to reassess.
Many people auto-renew their existing plan without comparing alternatives. Insurers can change premiums, deductibles, drug formularies, and provider networks from one year to the next. A plan you did not choose actively may cost more or cover less than it did previously.
If you have never purchased your own coverage before, the starter guide for first-time buyers is a useful foundation before working through the steps below.
What you will need
How to compare and choose your plan
The steps below walk through the process in the order that tends to work well for most people. Read them before your enrollment window opens so you know what information to gather in advance.
Confirm your enrollment window
Open enrollment dates differ by coverage type. The federal marketplace typically runs from November 1 through January 15 in most states, though some state-run exchanges set different end dates. Employer-sponsored plans follow their own schedules, usually in the fall. Medicare's Annual Enrollment Period runs October 15 through December 7 each year.
Missing a deadline generally means you cannot enroll until the following year unless you experience a qualifying life event such as a job loss, marriage, or birth of a child. Check your specific window before doing anything else.
Review what you actually used last year
Pull your Explanation of Benefits statements or medical bills from the past 12 months. Count your doctor visits, any procedures, emergency care, and total prescription costs. This gives you a realistic baseline for how much coverage you actually need, rather than guessing.
If your health situation changed (a new diagnosis, a planned surgery, a pregnancy), factor that into your estimate for the coming year.
Understand the cost structure of each plan
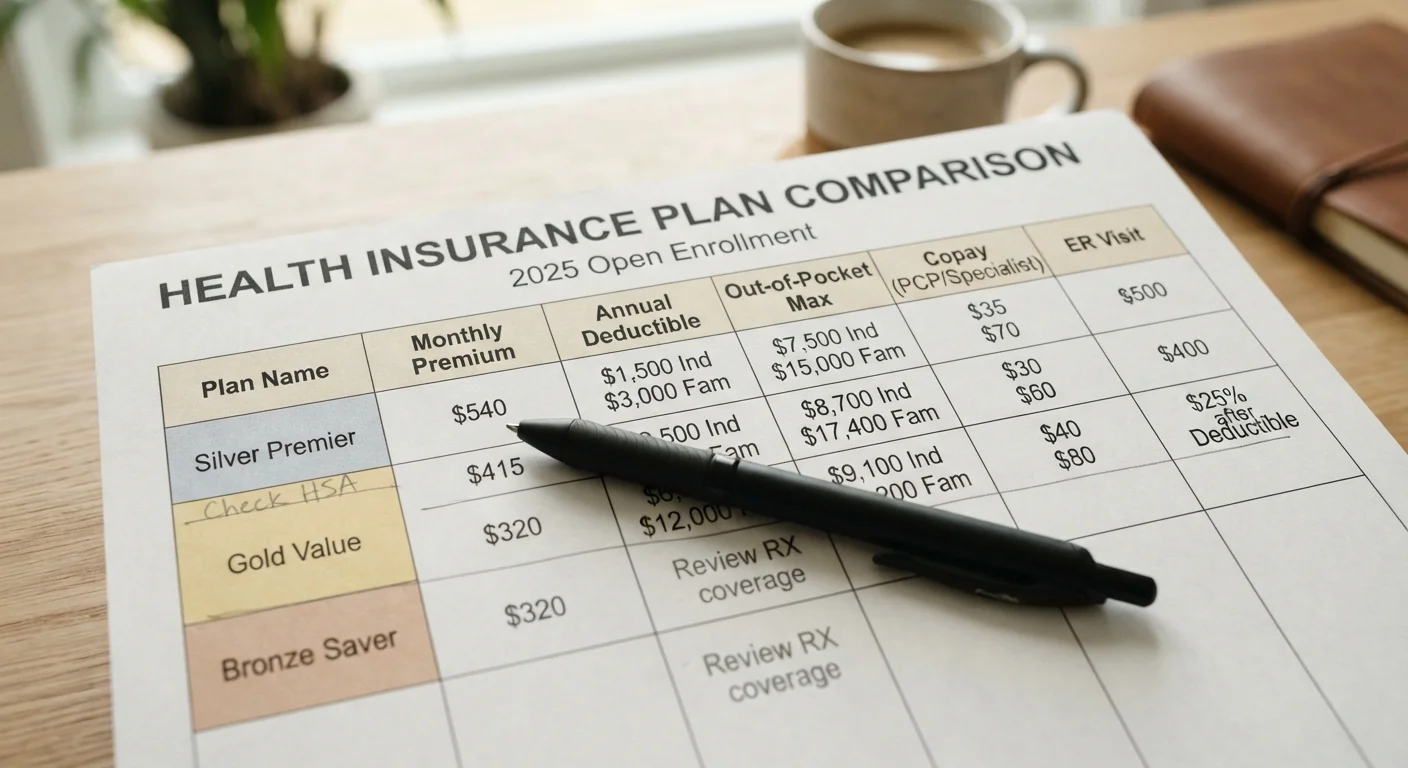
Every plan has four main cost-sharing components you need to compare together, not in isolation:
- Premium: the monthly amount you pay to keep the plan active, regardless of whether you use care.
- Deductible: the amount you pay out of pocket each year before the plan begins sharing most costs.
- Copays and coinsurance: fixed or percentage-based amounts you owe for covered services after meeting the deductible.
- Out-of-pocket maximum: the most you will pay in a plan year; the insurer covers 100% of covered in-network costs above this amount.
A plan with a low premium often has a high deductible. If you use medical services frequently, a plan with a higher premium and lower deductible may cost less overall by year's end. The Health Insurance Terms Every Policyholder Should Know explains each of these terms in plain language if any are unfamiliar.
Check network and drug coverage
Before selecting a plan, verify two things using the insurer's current directories. First, confirm that your primary care physician, specialists, and preferred hospitals appear as in-network providers. Out-of-network care can cost significantly more, and some plan types (such as HMOs) may not cover it at all outside emergencies.
Second, look up each of your medications in the plan's drug formulary. Formularies group drugs into tiers that determine your cost. A drug covered at a low tier on your current plan may be placed in a more expensive tier (or not covered) on a new plan.
Check subsidy or tax credit eligibility
If you are buying coverage through the federal or a state marketplace, you may qualify for a premium tax credit (sometimes called an advance premium tax credit, or APTC) based on your household income and size. The credit reduces your monthly premium cost.
The Health Insurance From Scratch guide covers eligibility basics for first-time buyers. If you are 65 or older and enrolled in Medicare, marketplace subsidies do not apply, but Medicare Savings Programs and Extra Help may be relevant. Seniors can also review what to look for in a Medigap plan for supplemental coverage options.
Complete and confirm enrollment
Once you select a plan, submit your application through the appropriate channel: your employer's benefits portal, HealthCare.gov, your state marketplace, or Medicare.gov for Medicare plans. Print or save your confirmation number and a copy of your enrollment summary.
Watch for your insurance card and welcome packet. Verify that your coverage effective date, plan name, and member ID are correct. If you spot an error, contact the insurer or marketplace immediately rather than waiting until you need care.
For a closer look at one common trade-off, the article on high-deductible health plans covers when that structure makes practical sense and when it may not. If you want to understand how a health savings account works alongside a high-deductible plan, see how HSAs work with your insurance.
Common enrollment errors (such as skipping drug coverage verification or misjudging network limits) are covered in detail in health insurance enrollment mistakes that leave gaps in coverage.
This article provides general health insurance information for educational purposes only. It is not personalized insurance, financial, or legal advice. Coverage terms, eligibility rules, and costs vary by plan and by state. Consult a licensed insurance agent or a certified navigator for guidance specific to your situation.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.