
Start here
Why health insurance works the way it does
Next
The cost terms you will see on every plan
Then
Types of health plans and how their networks differ
When you're ready
Where first-time buyers can get coverage
Before you enroll
What to check before you enroll
Why health insurance works the way it does
Health insurance is a contract: you pay a monthly premium, and the insurer agrees to share the cost of covered medical care. The system works because large groups of people pay into a common pool, and most members stay healthy in any given year. That pool funds care for those who do need it.
This structure has a practical consequence for first-time buyers. You will pay every month whether you use your insurance or not. In a year with no health events, your premium buys protection against what could happen, not a service you consumed. An unexpected hospitalization or surgery can cost tens of thousands of dollars; insurance converts that unpredictable risk into a known, manageable monthly cost.
The Affordable Care Act (ACA) added rules that changed what insurers can and cannot do. Plans sold to individuals and small groups must cover a set of essential health benefits, cannot charge more based on pre-existing conditions, and must cover preventive care at no cost-sharing. Those protections apply to any ACA-compliant plan you find on the Marketplace or through most employers.
This article is general information, not advice
The content here explains how health insurance works at a general level. It is not personalized insurance, financial, or medical advice. Plan rules, costs, and eligibility vary by state, insurer, and individual circumstances. Consult a licensed insurance agent or broker for guidance specific to your situation.
The cost terms you will see on every plan
Four numbers determine what you actually pay when you use healthcare. Knowing how they interact removes most of the confusion from plan comparison.
Premium
The monthly amount you pay to keep your health insurance active, regardless of whether you use medical services.
Deductible
The amount you pay out of pocket for covered care before your insurance starts sharing costs.
Copay
A fixed dollar amount you pay for a specific service, such as $30 for a primary care visit, at the time of care.
Coinsurance
Your share of costs after you meet your deductible, expressed as a percentage, such as 20% of the billed amount.
Out-of-pocket maximum
The most you will pay for covered services in a plan year; once you reach it, the insurer pays 100% of covered costs.
Network
The group of doctors, hospitals, and other providers that have agreed to contracted rates with your insurer.
Formulary
The list of prescription drugs your plan covers, usually divided into tiers that determine your cost-share.
Qualifying life event
A life change such as losing job-based coverage, getting married, or having a child that opens a special enrollment window outside of open enrollment.
The premium is your fixed monthly cost. The deductible is what you pay before the insurer contributes. Once you meet the deductible, you typically split costs with the insurer through either a copay (a flat fee per visit) or coinsurance (a percentage of the bill). The out-of-pocket maximum caps your total annual exposure: after you hit it, the insurer covers 100% of eligible costs for the rest of that plan year.
A plan with a low premium often carries a higher deductible. That trade-off suits someone who rarely needs care and wants to keep monthly costs down. A plan with a higher premium and lower deductible generally costs less per visit, which can be useful if you have ongoing prescriptions or regular specialist appointments. Neither structure is objectively better; the right balance depends on your expected usage. For a deeper look at these and other terms, the health insurance terms glossary covers the full vocabulary.
Types of health plans and how their networks differ
Plan type determines how you access care, not just how much it costs. The most common structures in the individual and employer markets are:
- HMO (Health Maintenance Organization): You select a primary care physician (PCP) who coordinates your care. Referrals are required to see specialists. Out-of-network care is not covered except in emergencies. Premiums are usually lower than other plan types at comparable coverage levels.
- PPO (Preferred Provider Organization): You can see any provider, in-network or out-of-network, without a referral. Out-of-network visits cost more but are covered. Premiums tend to be higher.
- EPO (Exclusive Provider Organization): Similar to an HMO in that out-of-network care is not covered, but you generally do not need referrals. The network is fixed and exclusive.
- HDHP (High-Deductible Health Plan): A plan with a higher deductible that qualifies you to open a Health Savings Account (HSA). An HSA lets you set aside pre-tax money for medical expenses.
Before enrolling in any plan, confirm that your current doctors and any hospitals you prefer are in-network. Network status changes from year to year, so verify directly with the provider and the insurer rather than relying on last year's directory.
Read the Summary of Benefits first
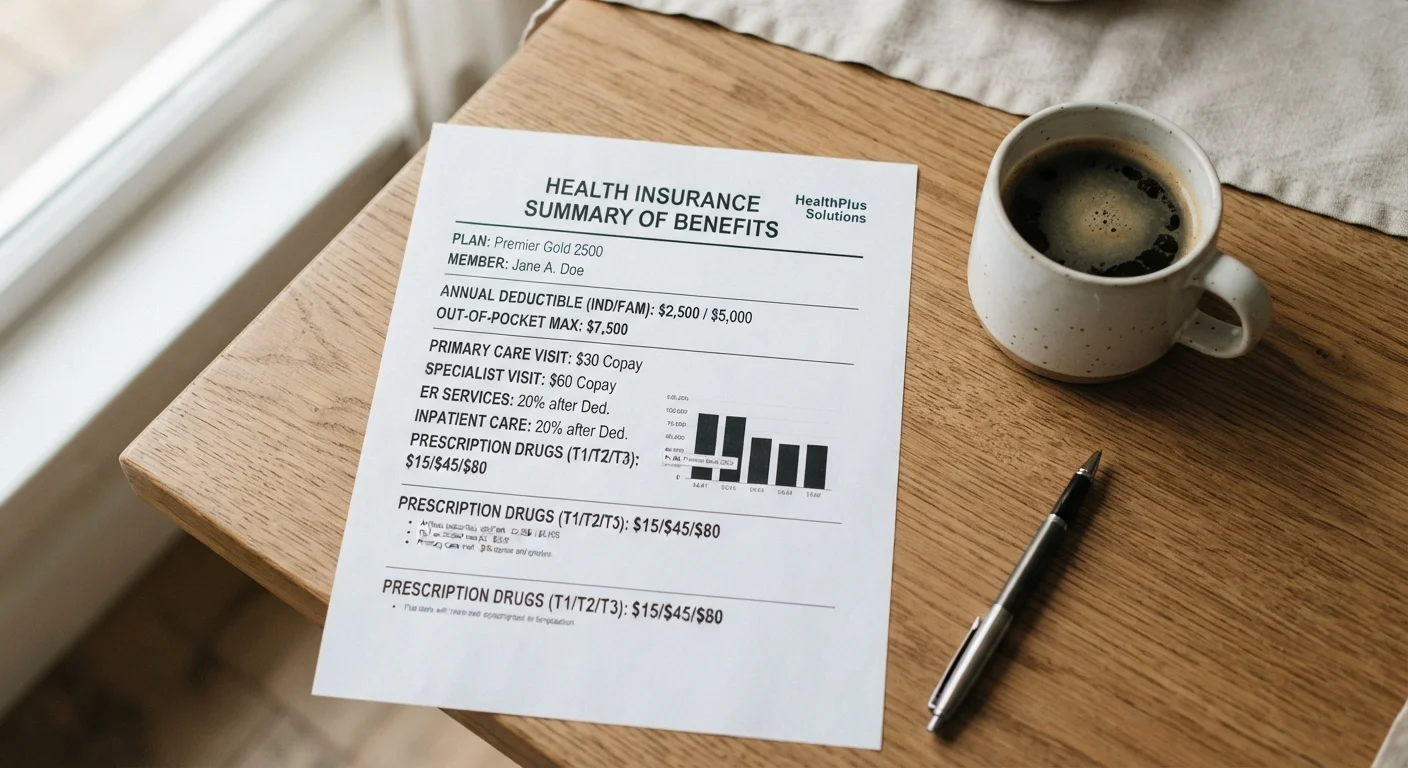
Every plan sold on the ACA Marketplace or through an employer must provide a standardized Summary of Benefits and Coverage (SBC) document. The SBC uses a common format across all plans, so it is the most reliable way to compare what you will actually pay for common scenarios like a primary care visit or a hospital stay.
Where first-time buyers can get coverage
Most Americans under 65 have four main paths to coverage.
Employer-sponsored insurance is the most common source. If your employer offers a plan, your premium share is deducted pre-tax from your paycheck. Your employer typically pays part of the premium as well. If you want to understand how that deduction appears on your pay stub, the first paycheck field guide explains each withholding line.
ACA Marketplace plans are available to people who do not have affordable employer coverage or who are self-employed. Premium tax credits are available to households between 100% and 400% of the federal poverty level, and in some years expanded subsidies have extended further up the income scale. Check HealthCare.gov or your state's Marketplace to see what you qualify for.
Medicaid covers people with incomes below a certain threshold, which varies by state. In states that expanded Medicaid under the ACA, the threshold is generally 138% of the federal poverty level. There is no enrollment period for Medicaid; you can apply at any time.
A parent's plan is an option if you are under 26. The ACA allows young adults to remain on a parent's employer or individual plan until their 26th birthday, regardless of where they live or whether they are in school.
Enrollment windows close quickly
The ACA's annual open enrollment period for Marketplace plans runs for a limited time each fall, and employer open enrollment windows are often even shorter. Missing your window without a qualifying life event means you generally cannot enroll until the next cycle. Mark the dates in advance and do not wait until the last day.
What to check before you enroll
Once you have narrowed down plan options, a few concrete checks reduce the chance of post-enrollment surprises.
First, confirm network status for any providers you use regularly. Search the insurer's online directory and call the provider's office to verify, since directories can lag behind actual contract status.
Second, check the formulary for any prescription medications you take. Formularies are tiered, and a drug covered at a low cost on one plan may sit in a higher-cost tier on another. Generic equivalents and step-therapy requirements can affect your access, so read the drug list carefully.
Third, calculate your realistic annual cost, not just the monthly premium. Add up 12 months of premiums plus your likely out-of-pocket spending based on your usage. For someone with predictable needs, this estimate is more useful than premium alone.
Fourth, note the plan's metal tier on the Marketplace (Bronze, Silver, Gold, or Platinum). These tiers describe the cost-split between you and the insurer, with Bronze plans covering roughly 60% of average costs and Platinum plans covering around 90%. Silver plans are the only tier eligible for cost-sharing reductions if your income qualifies.
The open enrollment comparison guide walks through how to apply these checks when your enrollment window opens. For a list of common enrollment mistakes to avoid, see health insurance enrollment mistakes.
This article provides general information about health insurance and is not personalized insurance, financial, or medical advice. Coverage terms, costs, and eligibility rules vary by plan, insurer, and state. Consult a licensed insurance agent, broker, or your state's consumer assistance program for guidance tailored to your circumstances.
Frequently Asked Questions
A deductible is the amount you pay for covered services before your insurer begins sharing costs. For example, with a $1,500 deductible, you pay the first $1,500 of eligible bills yourself. After that, cost-sharing through copays or coinsurance applies.
Outside of open enrollment, you can only sign up for a plan if you have a qualifying life event such as losing a job, getting married, or having a baby. Without one, you may have to wait until the next open enrollment period. Missing the window is one of the most common enrollment mistakes.
An unexpected illness or injury can generate medical bills that far exceed a year's worth of premiums. Health insurance protects against that financial risk regardless of age. The ACA also requires plans to cover preventive care at no cost-sharing, which has long-term health value.
An HMO requires you to choose a primary care physician and get referrals to see specialists; care outside the network is generally not covered. A PPO gives you more flexibility to see out-of-network providers, usually at a higher cost-share.
The Marketplace is a federally run (or state-run) platform where individuals and families can compare and purchase health plans that meet ACA standards. Depending on your income, you may qualify for subsidies that reduce your monthly premium.
Under the ACA, young adults can remain on a parent's plan until age 26, regardless of whether they live at home, are in school, or are employed. Contact the parent's insurer or employer HR department to confirm the process.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.